
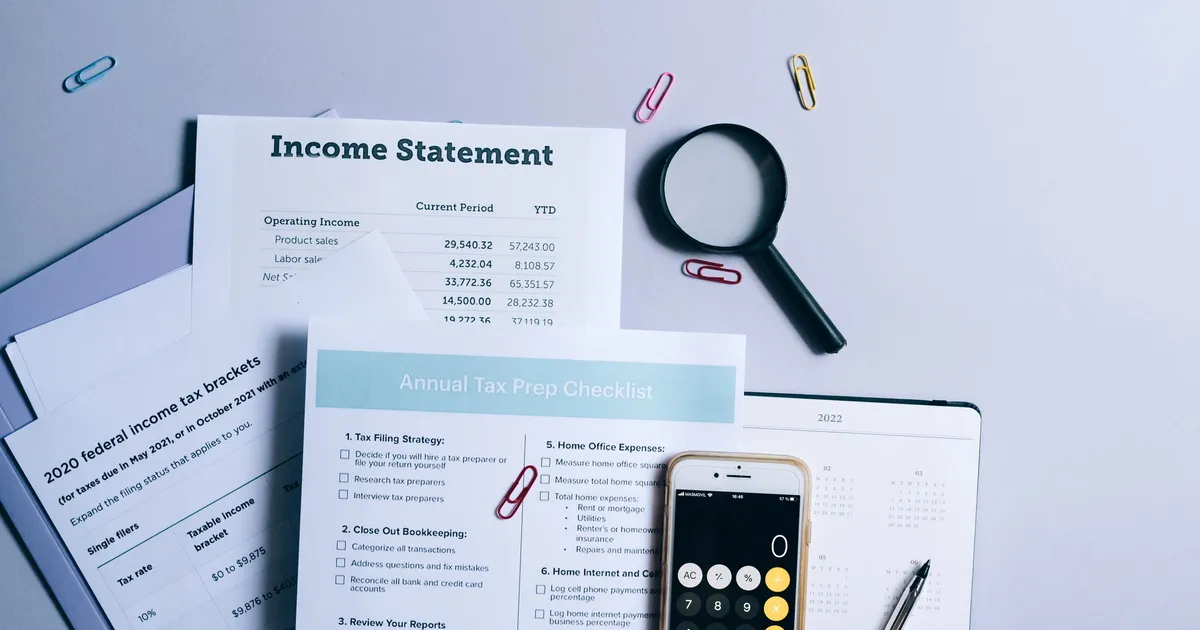
Understanding US Federal Tax Brackets (And Why You Don't Pay One Flat Rate)
The Most Common Tax Misconception
A huge number of people believe that moving into a higher tax bracket means all of their income suddenly gets taxed at that higher rate -- and that a raise could actually leave them with less money. This is false, and understanding why is one of the most useful pieces of financial literacy you can have.
How Marginal Brackets Actually Work
The US federal income tax system is "progressive" and "marginal": each bracket's rate applies only to the slice of income that falls within that bracket, not your entire income. If the 22% bracket starts at $50,400, earning $50,401 doesn't mean all $50,401 is taxed at 22% -- only that last $1 is. Everything below that threshold is still taxed at the lower brackets' rates, exactly as before.
A Concrete Example
Say brackets are 10% up to $12,400, then 12% up to $50,400, then 22% beyond that. Someone earning $55,000 pays 10% on the first $12,400, 12% on the next portion up to $50,400, and 22% only on the remaining $4,600 above that -- not 22% on the full $55,000. Use the Federal Tax Bracket Calculator to see this breakdown for your own income.
Marginal Rate vs Effective Rate
Your "marginal rate" is the rate on your last dollar of income (the highest bracket you reach). Your "effective rate" is your total tax divided by your total income -- almost always meaningfully lower than your marginal rate, precisely because of how brackets stack. The Income Tax Calculator shows both.
So Can a Raise Ever Reduce Your Take-Home Pay?
No -- under the US federal system, earning more always results in more after-tax income, never less. (A separate, real phenomenon -- losing eligibility for an income-capped benefit or credit -- can sometimes offset a raise, but that's a different mechanism than tax brackets themselves.)
Filing Status Changes the Brackets
The income ranges for each rate are not the same for everyone. Single filers, married couples filing jointly, married filing separately, and heads of household each have their own thresholds. In general, joint filers get wider ranges, so more income is taxed at lower rates before moving up. Always look up the correct table for your status at the IRS page linked in this article, because the exact numbers are adjusted periodically.
Taxable Income Is Not Your Salary
Brackets apply to taxable income, which is what remains after subtracting the standard deduction (or itemized deductions) and certain adjustments from your gross income. That means someone earning a given salary can land in a lower bracket than they expect. The Taxable Income Calculator on this site helps you find that starting number before you apply any brackets.
Working Through an Example Step by Step
Using a small hypothetical bracket table, suppose the rates are 10 percent up to 10,000 dollars, 12 percent from 10,000 to 40,000 dollars, and 22 percent above that. These numbers are invented for illustration and are not real bracket thresholds. Someone with 55,000 dollars of taxable income would compute:
- 10 percent of the first 10,000 dollars is 1,000 dollars.
- 12 percent of the next 30,000 dollars is 3,600 dollars.
- 22 percent of the remaining 15,000 dollars is 3,300 dollars.
- Total tax: 7,900 dollars, an effective rate of about 14.4 percent, even though the marginal rate is 22 percent.
Why a Raise Never Costs You Money on Income Tax Alone
Because only the dollars above a threshold are taxed at the higher rate, earning more always leaves you with more after federal income tax. There are a few places where losing a benefit, such as a credit that phases out, can make the real gain smaller, but a bracket jump on its own is never the cause.
Different Kinds of Income, Different Rules
Not all income is taxed at the ordinary brackets. Long-term capital gains and qualified dividends generally have their own lower rate schedule, while short-term gains are typically taxed like ordinary income. Self-employment income also carries an additional payroll-style tax. If you have investments or freelance income, use the specialized calculators rather than the plain bracket tool.
Ways People Manage Their Bracket Exposure
- Pre-tax contributions to a 401(k), Traditional IRA, or HSA reduce taxable income if you are eligible.
- Timing income and deductions across years, when you have that flexibility, can smooth out taxable income.
- Tax credits reduce your bill directly and are worth looking for.
Common Mistakes
- Believing you should turn down a raise or bonus to avoid a higher bracket.
- Confusing withholding rate with actual tax owed.
- Looking at last year's brackets instead of the current table.
- Forgetting that state taxes have their own separate brackets or flat rates.
When to See a Professional
If you are near a bracket edge because of a one-time event, such as selling a home, exercising stock options, or receiving a large distribution, a licensed tax preparer can help you plan around it. This article is general education, not tax advice.
Thinking About Marginal Rates When Making Choices
Your marginal rate is useful for one thing in particular: estimating what an extra dollar of income or deduction is worth. If your top rate is 22 percent, a 1,000 dollar pre-tax retirement contribution reduces your federal tax by roughly 220 dollars, a hypothetical illustration. This is why people near a lower bracket edge sometimes compare a Traditional and a Roth contribution. Use the marginal figure for decisions about extra income or deductions, and the effective rate for understanding your overall tax burden.
A Quick Way to Sanity-Check Your Own Tax
After you find your tax with a calculator, divide it by your taxable income to get your effective rate, and compare that with your top bracket. The effective rate should be noticeably lower. If it is not, or if it is higher than your top marginal rate, something was entered incorrectly, such as gross income used in place of taxable income. This simple check catches many mistakes in a few seconds. It also reminds you that brackets describe how income is sliced, not a single rate applied to everything you earned during the year, and that credits and other taxes sit outside the bracket table entirely.
Frequently Asked Questions
Where can I find the current year's exact bracket thresholds?
The IRS publishes updated brackets annually -- thresholds are adjusted for inflation each year.
Do state income taxes work the same way?
Many states with income tax also use progressive brackets, though some use a single flat rate instead -- check your specific state's rules.
Do brackets apply to my salary or my taxable income?
Taxable income, which is what remains after the standard or itemized deduction and certain adjustments.
Do capital gains use the same brackets?
Long-term gains and qualified dividends generally use their own, lower rate schedule, while short-term gains are typically taxed as ordinary income.
Do state taxes use these brackets?
No. States set their own rates, and some have none.
Where can I find current brackets?
The IRS page linked in this article lists the current tables for each filing status.
Comments (0)
No comments yet. Be the first to share your thoughts.